About Theory A
Connect the business to the trade.
Compare company fundamentals with options pricing, on the same timeline.
Explore earnings, valuation, and option breakevens together. Change your assumptions and see where your view of a business differs from the price of a trade.
Explore the stock analyzer →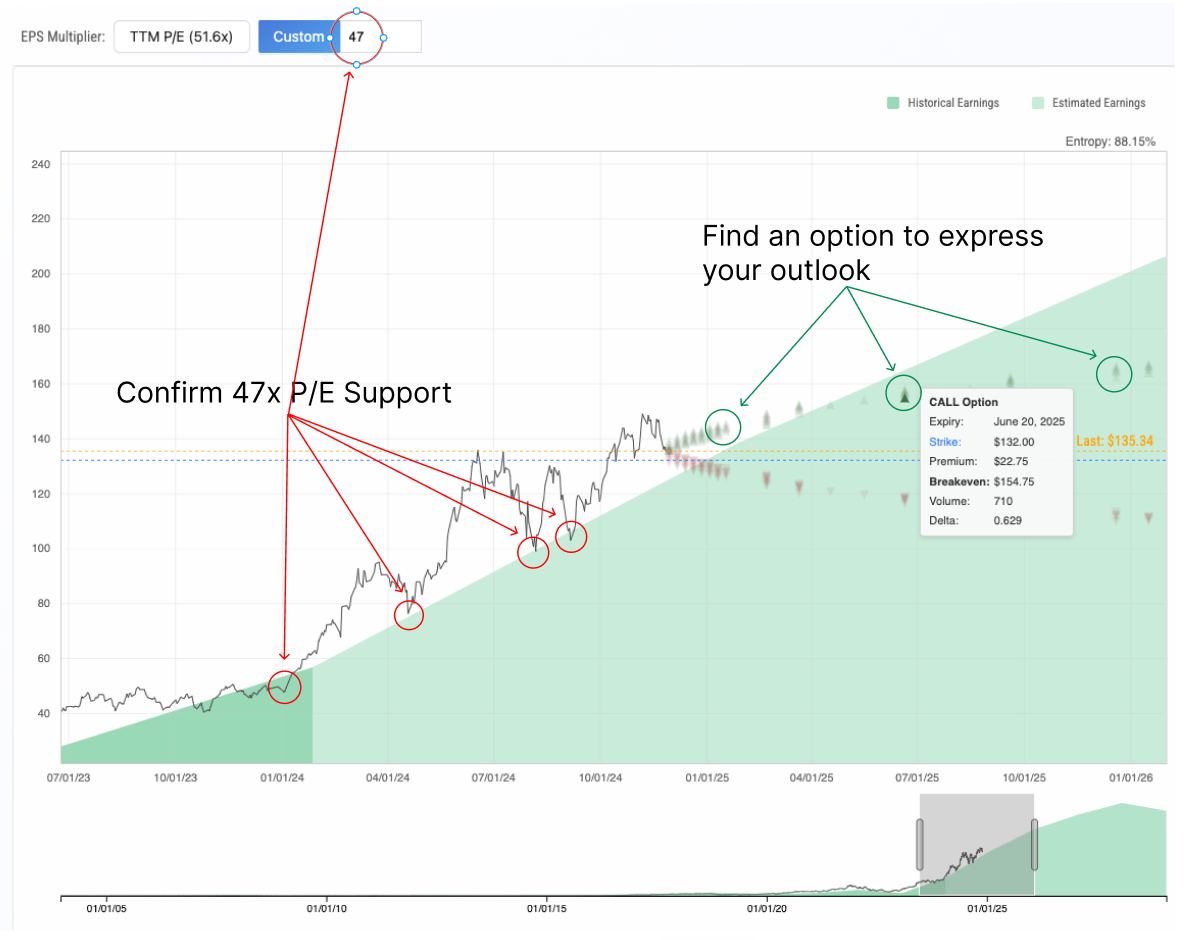 View full-size chart ↗
Fundamentals and options, on the same chart
Start with a business scenario, then examine how different instruments behave if it unfolds. For example, what if earnings grow more slowly than expected, or the market assigns a lower multiple even as earnings rise?
- Separate reported earnings from analyst estimates and your own projections.
- Compare several growth and valuation assumptions, including a downside scenario.
- Match the time horizon of your thesis to the expirations you are examining.
- Compare the payoff, maximum loss, and capital required for each position.
What does an earnings multiple tell you?
Imagine a business with $1.2 million in annual revenue and $1 million in total expenses. Its annual profit is $200,000. At a $3 million valuation, its price-to-earnings ratio (P/E) is 15: you are paying $15 for each dollar of annual earnings.
That is not a promise to recover your investment in 15 years. Earnings can change, profits may be reinvested, and accounting earnings differ from cash available to shareholders. A multiple is a way to frame a question, not a universal buying rule.
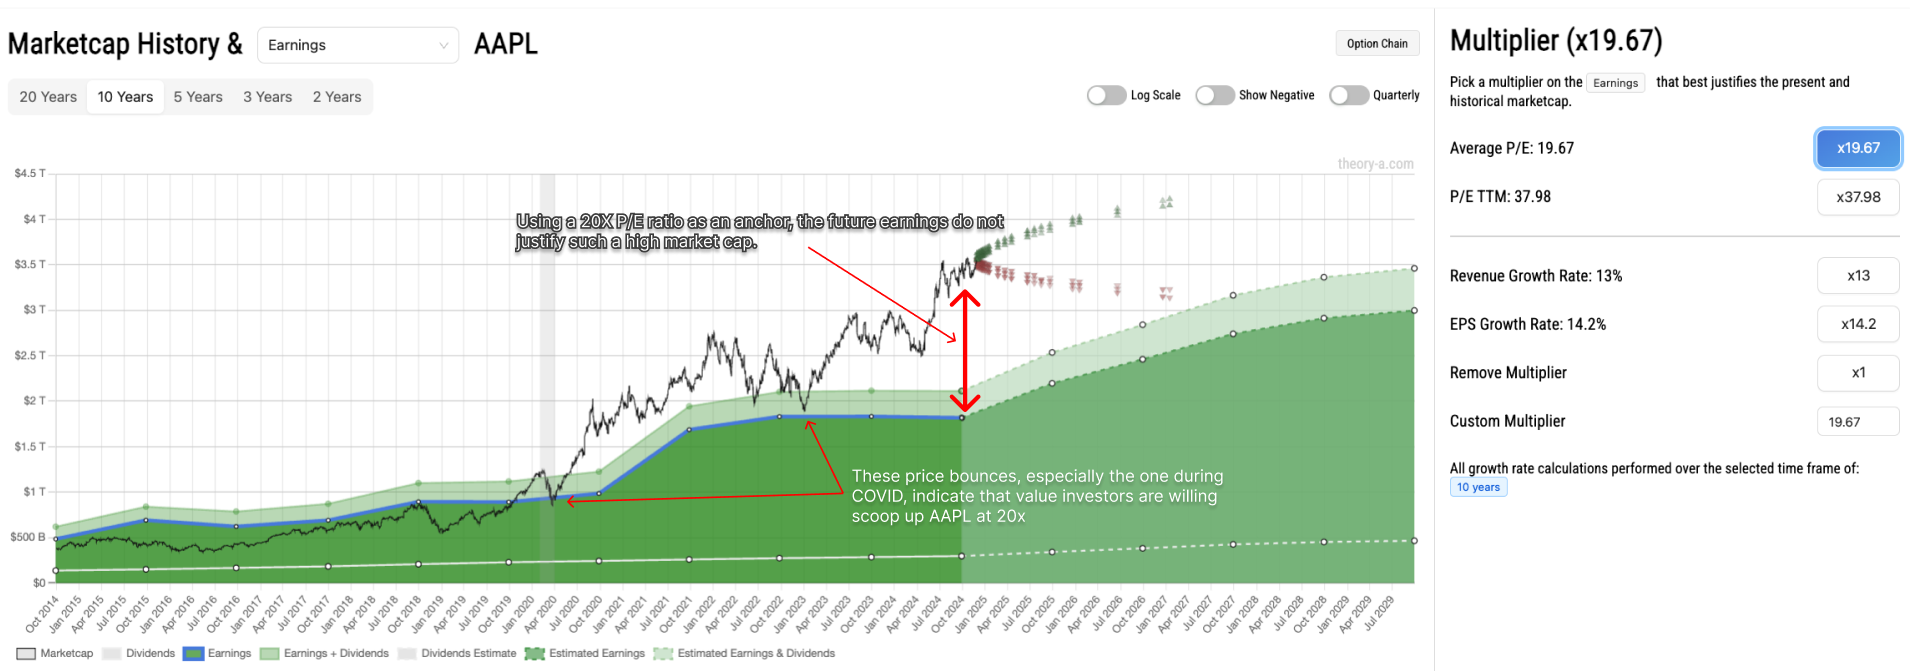
In Theory A, you can compare market capitalization with earnings multiplied by a selected P/E. Try several multiples and ask what would justify each one: growth, profitability, capital needs, debt, and uncertainty all matter.
 View full-size chart ↗
The gap between the price line and an earnings overlay depends on the chosen multiple. The estimated section also depends on forecasts that can be revised. A high valuation may reflect expectations of future growth; a chart alone cannot establish whether those expectations will be met. The further a thesis reaches into the future, the more room there is for assumptions to change.
Reading option breakevens
For a purchased call held to expiration, the breakeven is the strike plus the premium per share. For a purchased put, it is the strike minus the premium. These simple calculations exclude fees and assume the contract is held to expiration.
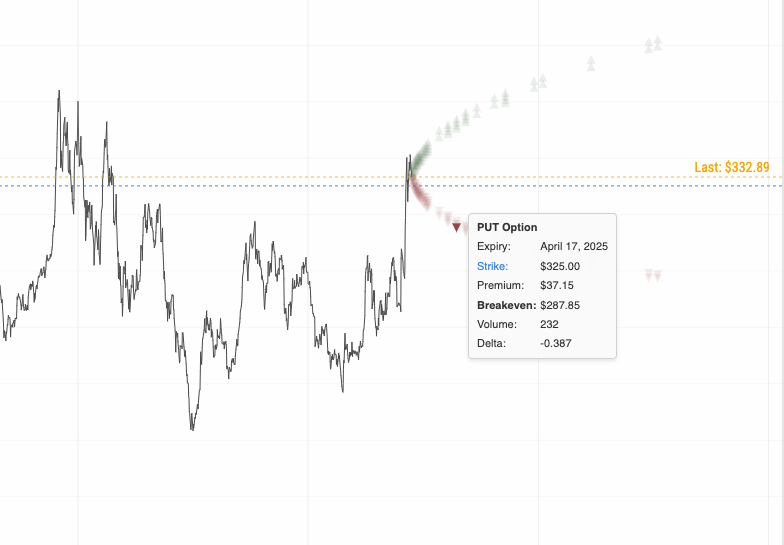
In the historical Tesla example below, a $325 put expiring April 17, 2025 was displayed with a premium of roughly $37 per share. Its expiration breakeven was therefore about $288. Before expiration, its value also depended on time remaining and implied volatility.
 View full-size chart ↗
Plotting breakevens across expirations helps compare the movements needed to cover different premiums. The resulting shape is not a statistical confidence interval or a direct forecast. Quotes reflect volatility, time, supply, demand, and other factors.
Go deeper: option pricing and straddles
Black–Scholes is one model for estimating theoretical option values, not a rule that determines all traded premiums. American-style options can be exercised early and are commonly modeled with methods that account for that feature. The Options Industry Council explains these distinctions in its introduction to option pricing models.
A long straddle buys a call and put at the same strike and expiration. At expiration, the stock must move beyond the strike by more than the combined premium to earn a profit before fees. Before then, both volatility and time decay affect its value. Selling the straddle reverses the payoff and introduces substantial loss exposure; collecting a premium does not ensure a profit. See the OIC’s straddle payoff explanation.
Comparing shares with long-term options
Long-term options, often called LEAPS, can provide exposure with a smaller initial outlay than buying shares. But $1,000 in calls is not automatically equivalent to $5,000 in stock. Exposure depends on the number of contracts, the contract multiplier, and delta, which changes as the stock price, time, and volatility change.
A purchased option can lose its entire premium, including when a bullish view proves right too late. Shares and calls also differ in dividends, voting rights, and expiration. For the tradeoffs, read the OIC’s overview of LEAPS and their risks.
Why we built Theory A
A stock price alone tells you little about the business behind it. A table of financial ratios can leave you with just as many questions. Theory A began with a simple idea: financial data becomes more useful when you can see it in context.
We started with visual tools for value investing and expanded into options analysis to connect two questions: what assumptions could justify a company’s valuation, and what price movements are reflected in options premiums? Seeing both helps you examine where your own expectations differ from the market.
Built for investors who want to understand their decisions
Theory A is for self-directed investors researching individual companies and options. You can use the fundamental tools on their own or bring options into your research as you become familiar with how they work.
- Find companies by comparing financial metrics and their position relative to other stocks.
- Examine a valuation using historical earnings, estimates, and adjustable valuation multiples.
- Explore options across strikes and expirations, including premiums, breakevens, and Greeks.
- Track a portfolio and use the options journal to review positions and trades.
Our data and methodology
Financial Modeling Prep supplies company fundamentals, historical prices, and analyst estimates used in our research tools. Our U.S. options chain uses Alpaca’s indicative options feed. Data is cached and refreshed at different intervals; displayed values may be delayed and can differ from executable quotes at your broker.
Valuation overlays apply a selected multiple to earnings or another financial measure. Historical results, analyst estimates, and assumptions you enter have different roles: reported results describe the past, while estimates and scenarios explore possible futures. Changing a multiple changes the scenario; it does not establish a fair price.
Option breakevens combine a contract’s strike and premium. They describe an expiration payoff threshold, not the probability that a stock will reach that price. Estimates, quotes, and calculated values can change as new information arrives.
Some company explanations and research summaries use AI. Treat these as starting points for research and verify material claims against company filings and original sources.
Who’s behind Theory A
Theory A is operated by Theory A, LLC. We build tools that help individuals explore financial data and form their own views.
For product questions, feedback, or data corrections, contact support@theory-a.com. You can also review our plans, privacy policy, and terms of service.
Theory A is a research tool and does not provide personalized investment advice. Models depend on their assumptions, and investments can lose value. Theory A, LLC is not a broker-dealer or registered investment adviser.